 blog
Is Buying a Colorado Luxury Home Worth It?
Last Updated: October 25, 2026
Quick Summary
Colorado luxury homes are worth buying when location, architecture, lot size, and finishes justify the price tier, since luxury is a local marketing tier rather than a statewide number. County choice drives taxes, short-term rental rules, and resale liquidity, so compare true ownership costs before touring.
- Luxury is a marketing tier that shifts by county, not a legal category.
- Verify short-term rental licensing and caps before underwriting resort rental income.
- Metro districts add a separate mill levy that can run for decades.
- A standard inspection does not cover wildfire risk, soils, water rights, or access easements.
- Request two years of utility bills, insurance premiums, and HOA financials before closing.
Table of Contents
- What Counts as a Colorado Luxury Home
- Colorado Luxury Homes by County: Where the Inventory Sits
- Denver Luxury Homes for Sale: Urban Listings and Pricing
- Buying a Luxury Home in Colorado: Process, Financing, and Due Diligence
- Colorado-Specific Property Risks Buyers Miss
- Ownership Costs and What the Listing Price Does Not Show
- Get a Free Home Valuation Before You Buy
- Frequently Asked Questions
What Counts as a Colorado Luxury Home
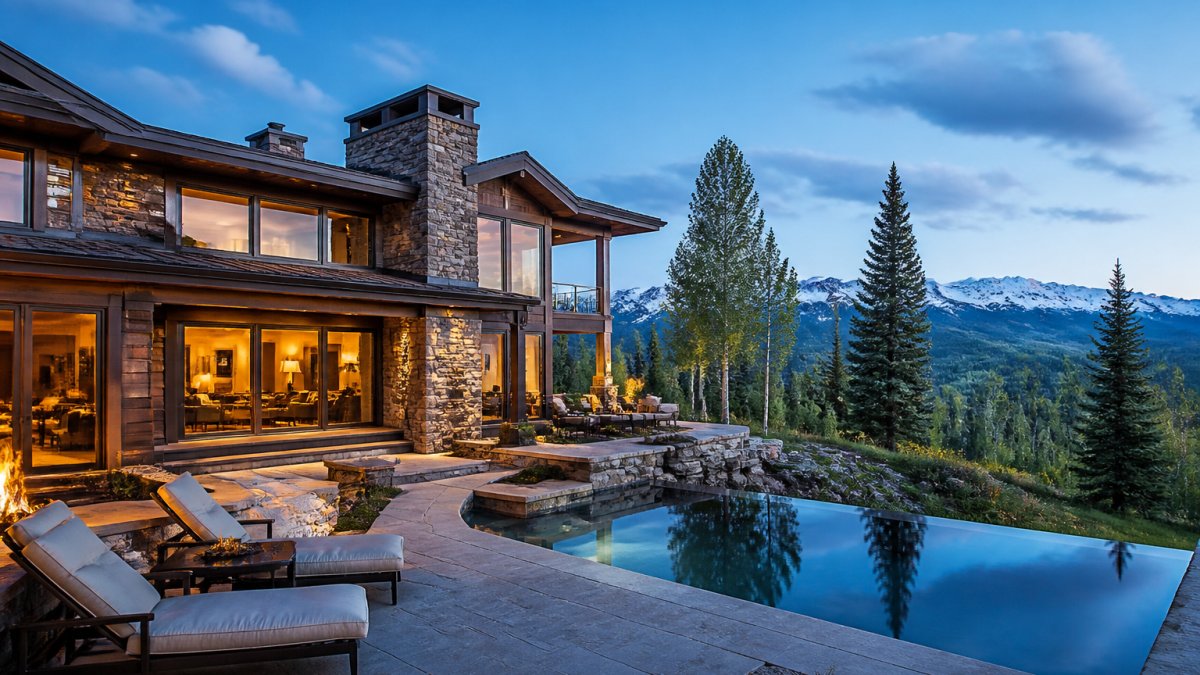
A Colorado luxury home is a residence priced in the top tier of its local market, typically defined by location, architecture, lot size, and finishes rather than by a single statewide number. In practice, that means a mountain estate in Summit County and a Cherry Creek townhome can both qualify, even at very different price points.
That definition matters because the label "luxury" is not a legal category. It is a marketing tier, and it shifts by county. At Purple Mtn Group, we treat luxury as a set of buyer expectations: privacy, craftsmanship, views, and access.
Three traits separate elite homes from the rest of the inventory:
- Location premium: ski-in access, foothills acreage, or a walkable urban core
- Architectural style: custom build, architect-designed, or a rare historic property
- Finish level: chef's kitchens, spa baths, smart-home systems, and guest quarters
Buyers who skip this definition often overpay for square footage in the wrong neighborhood.
Colorado Luxury Homes by County: Where the Inventory Sits
Inventory for Colorado luxury homes clusters in a handful of counties, and each one behaves differently in price tier, product type, and regulation. The county line is not just a map boundary, it determines the assessor who values the property, the mill levy you pay, the services you receive, and often the short-term rental rules that govern resort income. Buyers who compare counties on price alone miss the operating cost and resale-liquidity differences that separate these markets.
Here is how the major luxury counties differ in practice:
- Denver County: Urban product, Cherry Creek townhomes, Washington Park bungalows, Highlands new-builds. Inventory turns faster, buyer pools are deeper, and valuation is driven by neighborhood, view corridors, and renovation quality. Property tax is assessed by the Denver Assessor's Office under state-level assessment rates.
- Summit County: Resort product, Breckenridge, Keystone, and Copper Mountain condos and ski-in/ski-out homes. Valuation leans on slope access and rental potential, and short-term rental licensing and caps are set at the county and town level, so verify the license before you underwrite rental income.
- Grand County: Winter Park and Granby Ranch inventory, a mix of resort condos and acreage. Buyer pools are thinner than Summit's, which affects days on market and resale timing.
- Jefferson County: Golden foothills acreage and foothills estates that blend privacy with a short commute. Larger lots bring well and septic systems, wildfire exposure, and expansive soils into the diligence scope.
- Boulder County: A constrained-growth market where the Boulder County Comprehensive Plan and city open-space purchases limit new supply, which supports resale values but narrows what is available at any given time.
- Pitkin and Eagle Counties: Aspen and Vail resort inventory, where the luxury tier is defined by proximity to lifts and core, and where short-term rental rules vary by municipality.
A resort-market example shows how different the product is: a ski-adjacent condo in Breckenridge trades on rental potential and slope access, not on lot size. You can view a Breckenridge resort listing to see how that inventory is priced and presented.
County matters for another reason: it drives taxes, services, and the rules that govern short-term rentals. Colorado assesses residential property at a statewide rate set by the legislature, but the mill levy is set locally by school districts, cities, counties, and special districts, so two homes of equal value in different counties can carry materially different tax bills.
Buyers comparing counties should ask four questions before touring:
- What is the current inventory at my target price tier, and how many days is it sitting?
- How deep is the buyer pool if I resell, and is the market driven by primary buyers or second-home buyers?
- Which county and municipal rules affect short-term rental licensing, caps, and occupancy?
- What is the total mill levy, including any metro district, and what does it fund?
A county-by-county comparison is more useful than a single statewide average because luxury pricing is local. The same square footage, finishes, and view premium can produce very different values and very different carrying costs depending on which side of a county line the property sits.
Denver Luxury Homes for Sale: Urban Listings and Pricing
Denver luxury homes for sale sit in a market where pricing is driven by neighborhood, view corridors, and building type more than raw square footage. Cherry Creek, the Highlands, and Washington Park anchor most of the urban luxury activity, with townhomes and single-family homes competing for the same buyers.
Pricing in the city behaves differently than in the mountains. Urban buyers pay for walkability, parking, and renovation quality; a renovated bungalow can command more than a larger house a few blocks away. If you want to ground the conversation in an actual property, review an urban Denver listing and its pricing rather than relying on averages.
A common mistake is comparing a Denver listing price to a mountain listing price and assuming one market is "cheaper." They are not the same product, and the valuation logic differs.
Buying a Luxury Home in Colorado: Process, Financing, and Due Diligence
Buying a luxury home in Colorado follows the same legal steps as any purchase, but the due diligence is heavier and the financing is less forgiving. Expect a longer inspection window, specialized appraisals, and a lender who understands jumbo and portfolio loans.
The sequence we walk buyers through:
- Pre-approval and proof of funds. Sellers of elite homes want to see capacity before they grant a tour.
- Property-specific due diligence. Well and septic inspections, radon tests, structural reviews, and HOA document review.
- Appraisal strategy. Luxury appraisals are harder to comp, so expect extra time and documentation.
- Offer terms. Escalation clauses, appraisal gaps, and closing timelines carry more weight than a small price bump.
A competitive offer in this tier is about certainty, not just price. Our competitive Denver home offer strategy guide walks through how to structure one. The Consumer Financial Protection Bureau guide to mortgage closing is a useful reference for the closing process and your rights as a borrower.
Colorado-Specific Property Risks Buyers Miss
Colorado's geography creates risks that a standard inspection may not fully surface. Altitude, soil, snow load, wildfire exposure, and water rights all affect value and insurability, and they vary block by block.
Wildfire exposure. Wildfire risk is mapped by state and federal agencies, and insurers increasingly use those maps plus their own models to set premiums, deductibles, and mitigation requirements.
Expansive soils. Common along the Front Range, expansive soils swell and shrink with moisture and can damage foundations and flatwork.
Well and septic systems. Rural properties may not connect to municipal water or sewer. A well inspection tests yield and water quality; a septic inspection evaluates the leach field and tank condition.
Snow load and roof age. Mountain homes need structural review before winter.
Water rights. In rural and mountain markets, water rights can be severed from the land or subject to ditch-company shares and augmentation requirements.
Access easements. Acreage and foothills properties sometimes rely on private roads or easements for access.
Short-term rental rules. County and municipal limits can affect resort income. Licensing requirements, caps, and occupancy limits vary by jurisdiction, so verify the current rules with the county or town before underwriting rental revenue.
A foothills property illustrates how these risks stack. You can review a Golden foothills property example to see the kind of acreage, access, and site conditions that require extra diligence. The practical takeaway is that Colorado-specific risks are insurable and financeable when they are identified early, and expensive when they surface at renewal or resale.
Ownership Costs and What the Listing Price Does Not Show
The listing price is the starting point, not the total. Ownership costs in Colorado include property taxes, HOA dues, metro district fees, insurance, utilities, and ongoing maintenance, and in mountain markets those costs can be substantial.
Metro district fees are the item buyers most often miss. For a deeper comparison of HOA versus metro district costs, see our dedicated guide. A new-build community may carry a metro district mill levy on top of standard property taxes, and that obligation can run for decades.
| Cost Category | What It Covers | What to Verify Before Closing |
|---|---|---|
| Property tax | County-assessed tax on value | Current assessment and any pending appeals |
| HOA dues | Shared amenities and maintenance | Reserve study and special assessment history |
| Metro district fees | Infrastructure debt and services | Mill levy, payoff schedule, disclosure |
| Insurance | Hazard, wildfire, and flood coverage | Wildfire zone rating and deductible |
| Maintenance | Roof, systems, snow removal | Age of roof, HVAC, and any deferred work |
A practical rule: request the last two years of utility bills, insurance premiums, and HOA financials. Sellers of luxury homes expect sophisticated buyers, and asking for this documentation signals you are serious.
Get a Free Home Valuation Before You Buy
A home valuation is the single most useful number in a luxury purchase, because it tells you whether the listing price reflects the market or the seller's hope. Purple Mtn Group provides accurate valuations and market insights across Denver, Golden, Summit, and Grand County, backed by 30 years of licensed experience and more than $250 million in sales.
Our team, led by Monica Graves as a member of the eXp Luxury Division, works with buyers and sellers on both sides of the transaction. That matters when you need a realistic read on a property before you make an offer.
Here is the challenge: luxury pricing is local, and generic estimates rarely capture view premiums, renovation quality, or county-specific costs. A Realtor.com market data search can show you list prices, but it will not tell you what a property is actually worth to you.
Get started with Purple Mtn Group and request a free home valuation before your next offer. Our team will walk you through the comps, and the risks specific to the property you are considering.
Frequently Asked Questions
What counts as a luxury home in Colorado?
There is no official threshold. In practice, Colorado luxury homes are defined by price tier relative to the local market, architectural style, lot size, and finishes. A home at $2 million in a Denver neighborhood may be considered entry luxury, while the same price buys a smaller mountain property in Summit County. Buyers should compare against recent comparable sales in the specific county rather than a statewide number.
Where can you find luxury homes for sale in Colorado?
Inventory concentrates in a few areas: Cherry Creek and the Denver metro, Boulder and Littleton, and the mountain and resort counties including Summit and Grand County. Colorado luxury homes by county vary widely in what the price buys, so start with the lifestyle and access you need, then compare current listings and valuations in two or three counties before scheduling tours.
What should buyers look for when purchasing a luxury home in Colorado?
Beyond finishes, check Colorado-specific risks: roof and snow load, foundation movement from expansive soils, wildfire mitigation and insurance availability, and well and septic systems in rural counties. Ask for a current home valuation and compare it with the listing price, review HOA rules for mountain communities, and confirm whether short-term rentals are allowed if that affects your plan.
How do you choose a real estate agent for a luxury home purchase?
Look for an agent with a track record in the specific county, not just the state. Ask how many luxury listings they have sold in the past year, whether they hold a luxury home marketing designation, and who will actually handle your showings and negotiations.